Welcome to the Walker Real Estate Group blog: your local resource for South Orange County real estate. 🏡 Every week we publish in-depth guides to San Clemente, Dana Point, and San Juan Capistrano, covering neighborhood-by-neighborhood breakdowns, current market data, and what it all means for buyers and sellers. You'll also find our monthly "Sold in South OC" report, tracking real sale prices and trends across all three cities. Whether you're buying your first home, selling, or just want to know what your property is worth, the goal is simple: clear local information you can act on.

March 3, 2025

San Clemente Housing Market Report – February 2025


Click Here to Search San Clemente Homes For Sale

The San Clemente real estate market remained strong in February 2025, showing signs of increased buyer activity despite shifting economic conditions. With home prices continuing to rise and properties selling faster than in previous months, it’s clear that demand remains steady in this coastal community.

Home Prices & Sales Activity

📈 Median Sales Price: $1,700,000 (Up 7.3% YoY)

💰 Price per Sq. Ft.: $803

🏡 Homes Listed: 74

🔑 Homes Sold: 45

📊 Sale-to-List Price Ratio: 97.5% of original asking price

Market Trends & Insights

February saw an increase in new listings, with 74 homes hitting the market, giving buyers more options. However, 45 homes sold, reflecting a steady turnover despite a competitive market.

The average days on market dropped significantly to just 16 days, compared to 35 days in January, indicating that well-priced homes are moving quickly. This trend suggests that motivated buyers are eager to secure homes in San Clemente before the spring market heats up further.

What This Means for Buyers & Sellers

🏡 For Sellers:

Homes are selling faster, meaning proper pricing and preparation are key.

With properties selling at 97.5% of asking price, pricing competitively can still yield strong offers.

🔑 For Buyers:

The market remains competitive, and homes are selling quickly.

With prices rising, acting sooner rather than later could help buyers secure better deals before further appreciation.

Looking Ahead

As we enter the spring market, San Clemente is expected to remain a seller’s market, with demand continuing to outpace inventory. Buyers should be prepared to act quickly, while sellers can benefit from strong pricing trends and reduced time on the market.


Considering buying or selling in San Clemente? Contact us today for expert guidance in this fast-moving market! 📲🏡
Click Here to Search San Clemente Homes For Sale

March 2, 2025

How to Get Pre-Approved for a Mortgage: What You Need to Know

Buying a home is an exciting journey, but before you start browsing listings, it’s essential to get pre-approved for a mortgage. Pre-approval not only helps you understand how much you can afford but also strengthens your offer in a competitive market. Here’s everything you need to know about getting pre-approved for a mortgage.

What Is Mortgage Pre-Approval?

Mortgage pre-approval is a process where a lender reviews your financial information—such as income, credit score, and debt—to determine how much they’re willing to lend you. It’s a crucial first step in homebuying that gives you a clear budget and signals to sellers that you’re a serious buyer.

Why Is Pre-Approval Important?

✅ Know Your Budget – Pre-approval helps you understand what home price range you can afford.
✅ Stronger Offers – Sellers prefer buyers with pre-approval because it shows financial readiness.
✅ Faster Closing Process – Since the lender has already reviewed your finances, the loan process is smoother.
✅ Better Loan Terms – Knowing your eligibility allows you to shop around for the best mortgage rates and terms.

Steps to Get Pre-Approved for a Mortgage

1. Check Your Credit Score

Lenders use your credit score to assess your financial health. A higher score improves your chances of securing a loan with favorable terms. Most conventional loans require a credit score of 620 or higher, while FHA loans accept scores as low as 500 with a higher down payment.

2. Gather Financial Documents

Lenders will request several documents, including:

Proof of income (pay stubs, W-2s, tax returns)

Employment verification

Bank statements

Debt obligations (credit cards, student loans, car loans)

Identification (driver’s license, Social Security number)

3. Determine Your Debt-to-Income Ratio (DTI)

Your DTI compares your monthly debt payments to your gross monthly income. Most lenders prefer a DTI under 43%, though lower is ideal for better mortgage terms.

4. Choose the Right Lender

It’s wise to shop around and compare lenders. Different lenders offer different interest rates and fees, so researching multiple options can save you thousands over the life of your loan.

5. Submit Your Application

Once you select a lender, you’ll complete a pre-approval application. The lender will conduct a hard credit inquiry, review your documents, and provide a pre-approval letter stating how much you can borrow.

What Happens After Pre-Approval?

Once pre-approved, your letter is typically valid for 60-90 days. During this time, you can confidently house hunt within your budget. If your financial situation changes (e.g., new debt or job loss), your loan approval could be affected, so avoid major financial moves until you close on a home.

Final Thoughts

Getting pre-approved for a mortgage is a crucial step in the homebuying process. It provides a financial roadmap, strengthens your offer, and helps ensure a smoother transaction. If you’re considering buying a home in South Orange County, start your pre-approval process today and position yourself for success! 🏡💰


Need help connecting with a lender? Reach out to us for expert guidance!

March 1, 2025

The Best Mortgage Loan Types for Homebuyers in 2025

Choosing the right mortgage is crucial for homebuyers, as it significantly impacts your financial future. In 2025, several mortgage options are available, each tailored to different needs and circumstances. Here's a comparison of FHA, VA, conventional, and jumbo loans to help you make an informed decision.

1. Federal Housing Administration (FHA) Loans

Overview: FHA loans are government-backed mortgages designed to assist first-time and low-to-moderate-income buyers.

Key Features:

Down Payment: As low as 3.5% of the purchase price.

Credit Score Requirements: Minimum credit score of 580 for the low down payment option.

Mortgage Insurance: Requires both an upfront premium (1.75% of the loan amount) and annual premiums (ranging from 0.45% to 1.05%).

Loan Limits: In 2025, the maximum loan size for most FHA borrowers is $524,225.
Mortgage Research

Ideal For: Buyers with lower credit scores or limited savings for a down payment.

2. Veterans Affairs (VA) Loans

Overview: VA loans are available to eligible veterans, active-duty service members, and certain members of the National Guard and Reserves.

Key Features:

Down Payment: No down payment required.

Credit Score Requirements: No official minimum, but lenders typically prefer a score of 620 or higher.

Mortgage Insurance: No monthly mortgage insurance; however, a one-time funding fee ranging from 0.50% to 3.6% applies.
The Mortgage Reports

Loan Limits: As of 2025, VA loans have no maximum loan amount, but lenders may impose their own limits.

Ideal For: Eligible military personnel seeking favorable loan terms without a down payment.

3. Conventional Loans

Overview: These are non-government-backed loans offered by private lenders, including conforming loans that meet Fannie Mae and Freddie Mac guidelines.

Key Features:

Down Payment: As low as 3% for first-time homebuyers.

Credit Score Requirements: Typically require a minimum credit score of 620.

Mortgage Insurance: Private mortgage insurance (PMI) is required if the down payment is less than 20%.

Loan Limits: In 2025, the maximum loan size for most conventional borrowers is $806,500.
Mortgage Research

Ideal For: Borrowers with good credit and the ability to make a modest down payment.

4. Jumbo Loans

Overview: Jumbo loans exceed the conforming loan limits set by the Federal Housing Finance Agency (FHFA) and are used for high-value properties.

Key Features:

Down Payment: Typically 20% or more.

Credit Score Requirements: Generally require a credit score of 700 or higher.

Mortgage Insurance: Not required, but higher interest rates may apply.

Loan Limits: Any loan amount exceeding the 2025 conforming limit of $806,500 is considered jumbo.
Mortgage Research

Ideal For: Buyers purchasing luxury homes or properties in high-cost areas.

Choosing the Right Loan

When selecting a mortgage, consider the following factors:

Credit Score: Higher scores open doors to more favorable loan terms.

Down Payment: Assess your savings to determine how much you can afford upfront.

Loan Amount: Ensure the loan aligns with your property value and conforms to relevant limits.

Eligibility: Some loans have specific requirements, such as military service for VA loans.

Consulting with a mortgage professional can provide personalized insights based on your financial situation and homeownership goals.

Note: Mortgage terms and conditions are subject to change. Always verify current information with a qualified lender.


Feb. 28, 2025

What Credit Score Do You Need to Buy a Home?

Your credit score plays a crucial role in determining whether you qualify for a mortgage and what interest rate you’ll receive. If you're planning to buy a home in South Orange County, understanding how credit scores impact the home-buying process can help you prepare financially and secure the best loan terms.

Why Your Credit Score Matters

Lenders use your credit score to assess risk—higher scores mean lower risk, which often leads to better interest rates and loan options. A lower score may require a higher down payment or result in higher monthly payments due to increased interest rates.

Credit Score Requirements for Different Loan Types

🔹 Conventional Loans – Typically require a minimum credit score of 620, though higher scores (700+) will get you better interest rates.
🔹 FHA Loans – Designed for first-time homebuyers, these loans allow for lower credit scores. You can qualify with a score as low as 500 with a 10% down payment or 580 with a 3.5% down payment.
🔹 VA Loans – Available for veterans and active-duty military, VA loans generally require a credit score of 580–620, though some lenders may accept lower scores.
🔹 Jumbo Loans – For high-value homes (common in South OC), jumbo loans often require a credit score of 700 or higher and a larger down payment.

How Credit Scores Affect Mortgage Rates

Your credit score significantly impacts the interest rate you qualify for. Here’s an example of how it can change your monthly mortgage payment on a $1,000,000 home with 20% down:

Credit Score

Estimated Interest Rate

Monthly Payment

760+

6.25%

$4,931

700-759

6.50%

$5,064

660-699

6.75%

$5,199

620-659

7.25%

$5,478

Rates are for illustrative purposes and subject to change based on market conditions.

Tips to Improve Your Credit Score Before Buying

✅ Pay Bills on Time – Payment history is the largest factor in your credit score.
✅ Reduce Debt – Lower credit utilization by paying down credit card balances.
✅ Avoid New Credit Inquiries – Applying for new credit before a mortgage can lower your score.
✅ Check Your Credit Report – Ensure there are no errors affecting your score.

Final Thoughts

A higher credit score can save you thousands of dollars over the life of your mortgage. If you're planning to buy a home in South Orange County, take steps now to improve your credit so you can secure the best financing options.


Thinking about buying? Contact us today to start your home search and get connected with trusted lenders! 📞🏡

Feb. 27, 2025

The Impact of Interest Rates on Selling Your Home


Interest rates play a crucial role in the real estate market, influencing buyer demand, home affordability, and overall market conditions. Whether you’re planning to sell your home in South Orange County or just keeping an eye on the market, understanding how mortgage rates impact home sales can help you make informed decisions.

How Interest Rates Affect Home Buyers

When interest rates rise, borrowing becomes more expensive, leading to higher monthly mortgage payments. This can reduce the number of qualified buyers and slow down home sales. Conversely, when interest rates drop, buyers can afford larger loans with lower payments, increasing demand and competition for homes.

Key Ways Interest Rates Influence Home Sales

📉 Buyer Demand – Higher interest rates often shrink the pool of potential buyers, as affordability declines. Lower rates encourage more buyers to enter the market, leading to increased demand.
🏡 Home Prices – In a high-rate environment, home prices may stabilize or decrease due to reduced buyer purchasing power. In contrast, lower rates can drive up home prices as buyers compete for available inventory.
⏳ Time on Market – Rising interest rates may result in longer listing times, as fewer buyers qualify for loans. Lower rates tend to speed up sales, as demand surges.
📊 Refinancing & Equity – When rates drop, existing homeowners are more likely to refinance, reducing the number of sellers in the market and tightening inventory. This can indirectly drive prices higher.

Selling Strategies in Different Rate Environments

✅ In a High-Rate Market:

Price competitively to attract buyers with tighter budgets.

Offer seller concessions, such as mortgage rate buy-downs, to make the home more appealing.

Highlight affordability features like energy efficiency and low maintenance costs.

✅ In a Low-Rate Market:

Consider listing at a premium, as more buyers can afford higher-priced homes.

Expect multiple offers and potentially faster sales.

Be strategic about timing—list when demand is strongest.

Should You Sell Now or Wait?

Deciding when to sell depends on your personal goals and market conditions. If rates are rising, selling sooner may help you avoid a slowdown. If rates are expected to drop, waiting could increase buyer competition and home values.

Final Thoughts

Interest rates are a major factor in determining the best time to sell your home. Staying informed about rate trends and adjusting your strategy accordingly can help you maximize your sale price and minimize time on the market.

Thinking of selling your home in South Orange County? Contact us today for expert advice and a customized selling plan! 🏡📈


Feb. 26, 2025

Buying a Home with an ADU in South Orange County

With the rising demand for multi-generational living and passive income opportunities, homes with Additional Dwelling Units (ADUs) have become increasingly popular in South Orange County. Whether you're looking to generate rental income, house extended family, or increase your property's value, buying a home with an ADU can be a smart investment. Here's everything you need to know about purchasing a property with an ADU in South OC.

What Is an ADU?

An Additional Dwelling Unit (ADU) is a secondary housing unit on a single-family lot. ADUs can be attached to the main home, detached in the backyard, or converted from existing space such as a garage. These units typically include a bedroom, bathroom, kitchen, and living area, making them fully functional residences.

Benefits of Buying a Home with an ADU

✅ Rental Income Potential – Renting out an ADU can provide a steady stream of passive income, helping to offset your mortgage or other expenses.
✅ Multi-Generational Living – ADUs offer a great solution for housing elderly parents, adult children, or extended family members while maintaining privacy.
✅ Increased Property Value – Homes with ADUs tend to have higher resale values due to their versatility and added living space.
✅ Flexible Use – Use the space as a home office, guest house, or short-term rental to maximize its benefits.
✅ Future-Proofing – With housing costs rising, an ADU can serve as a long-term housing solution for family members or an aging homeowner.

Best South OC Cities for ADU-Friendly Homes

If you're looking to buy a home with an ADU, consider these cities in South Orange County:

🏡 San Clemente – Offers coastal ADU opportunities with high rental demand.
🏡 Dana Point – Ideal for vacation rentals and multi-generational living.
🏡 Laguna Niguel – Features spacious lots that can accommodate detached ADUs.
🏡 Mission Viejo – Known for family-friendly communities with ADU potential.
🏡 San Juan Capistrano – Allows for more flexible zoning, perfect for ADU additions.

Financing a Home with an ADU

Purchasing a property with an ADU may require different financing options:

Conventional Loans – Some lenders allow rental income from the ADU to be factored into loan qualification.

FHA and VA Loans – These may be used for multi-unit properties if the buyer intends to live in one of the units.

ADU Construction Loans – If you're considering adding an ADU to a home, renovation loans or home equity loans can help finance the project.

Considerations Before Buying

Before purchasing a home with an ADU, keep these factors in mind: 🔹 Local Zoning Laws – Check city regulations regarding ADU use, short-term rentals, and parking requirements.
🔹 Permitting & Compliance – Ensure the ADU is legally permitted to avoid issues with financing and resale.
🔹 Property Management – If renting the unit, consider property management services for tenant screening and maintenance.

Is an ADU Home Right for You?

Buying a home with an ADU in South Orange County can be a great investment, offering both financial and lifestyle benefits. Whether you're looking for additional income, a place for family, or a future-proof property, an ADU home provides flexibility and value.


Ready to find your perfect ADU home in South OC? Contact us today to explore available listings! 🏡✨

Feb. 25, 2025

How Much Money Do You Need to Buy a Home in Southern California?

Buying a home is one of the biggest financial decisions you'll make, and understanding how much money you need upfront is crucial. In Southern California, where home prices are higher than the national average, saving for a 20% down payment can feel like a major hurdle. But what does that actually look like in real numbers? Let’s break it down with examples and estimate monthly payments based on current interest rates.


💵 How Much Is a 20% Down Payment?

A 20% down payment is the gold standard for homebuyers. While some loans allow for lower down payments, putting 20% down has key benefits:

✅ No Private Mortgage Insurance (PMI) – Saves you hundreds per month
✅ Lower Monthly Payment – Since you’re borrowing less
✅ Better Interest Rates – Lenders often offer lower rates to buyers with higher down payments

Here’s what a 20% down payment looks like at different price points:

Home Price

20% Down Payment

Loan Amount

$750,000

$150,000

$600,000

$1,000,000

$200,000

$800,000

$1,500,000

$300,000

$1,200,000

$2,000,000

$400,000

$1,600,000


💳 Monthly Payments After a 20% Down Payment

Your monthly mortgage payment depends on several factors, including interest rates, property taxes, and homeowners insurance. Let’s estimate monthly payments based on a 6.5% interest rate for a 30-year fixed loan (excluding taxes and insurance for simplicity).

Home Price

Loan Amount (After 20% Down)

Estimated Monthly Payment (Principal & Interest)

$750,000

$600,000

~$3,792

$1,000,000

$800,000

~$5,056

$1,500,000

$1,200,000

~$7,584

$2,000,000

$1,600,000

~$10,112

💡 These estimates are based on a 6.5% interest rate. Your actual payment may vary depending on your credit score, lender, and market conditions.


Other Costs to Consider When Buying a Home

Beyond the down payment and mortgage, here are other costs to keep in mind:

🔹 Closing Costs – Typically 2-3% of the home price (e.g., $15K–$30K on a $1M home)
🔹 Property Taxes – Around 1.1% of the home price annually in California
🔹 Homeowners Insurance – Varies, but ~$1,000–$2,500 per year
🔹 HOA Fees – If you’re buying in a community with a homeowners association


💡 Can You Buy with Less Than 20% Down?

Yes! Many buyers in Southern California put down 5-10%, or even as low as 3.5% with an FHA loan. However, this means:

🔸 Higher monthly mortgage payments
🔸 PMI (Private Mortgage Insurance) added to your payment
🔸 Less equity upfront

If you’re unsure which option is right for you, a local lender or real estate expert can help evaluate your financial situation.


Ready to Buy? Let’s Find Your Dream Home!


If you’re planning to buy a home in South Orange County or the surrounding areas, we can help you navigate the process, connect with top lenders, and find a home that fits your budget. Contact us today to start your journey to homeownership! 🏡✨

Click Here to Search Homes in Southern California

Feb. 24, 2025

Should You Sell Your House As-Is or Make Repairs First?

When selling your home, one of the biggest decisions you’ll face is whether to sell it as-is or invest in repairs before listing. While making updates can increase your home’s value, selling as-is can save time and effort. So, which option is best for you? Let’s break down the pros and cons of each strategy to help you decide.

Click Here to Check the Price of Your Home

Selling As-Is: Pros & Cons

✅ Pros of Selling As-Is

Faster Sale – No need to wait for renovations; list your home immediately.

Less Stress – Avoid the hassle of dealing with contractors, delays, and unexpected costs.

Attract Investors & Fixer-Upper Buyers – Some buyers specifically look for as-is properties to renovate themselves.

❌ Cons of Selling As-Is

Lower Sale Price – Buyers may offer less, knowing they’ll need to make repairs.

Fewer Interested Buyers – Many buyers prefer move-in-ready homes.

Potential Appraisal Issues – If the home needs major repairs, it may not qualify for financing.

Making Repairs Before Selling: Pros & Cons

✅ Pros of Making Repairs

Higher Sale Price – Updated homes typically sell for more.

More Buyer Interest – Move-in-ready homes attract more offers.

Easier Negotiations – Fewer repair-related contingencies from buyers.

❌ Cons of Making Repairs

Upfront Costs – Renovations can be expensive, and you may not fully recoup the investment.

Longer Time to Sell – Completing repairs can delay listing your home.

Unpredictable Issues – Unexpected problems may arise, leading to higher costs.

What Repairs Are Worth Doing?

If you decide to make updates, focus on high-impact, cost-effective improvements such as:
✔ Painting – A fresh coat of neutral paint brightens the space.
✔ Landscaping – Boost curb appeal with trimmed shrubs and fresh mulch.
✔ Minor Kitchen/Bath Updates – Replacing hardware or refinishing cabinets can make a big difference.
✔ Flooring Repairs – Fixing worn-out carpet or refinishing hardwood floors enhances value.

So, What’s the Right Choice?

Sell As-Is if you need to move quickly, don’t have the budget for repairs, or are selling an older home that needs extensive work.

Make Repairs First if you want to maximize your sale price, attract more buyers, and have the time and budget for updates.

Every home is unique, and the right strategy depends on your goals. If you're unsure which option is best for your situation, let’s connect and discuss your home’s value and selling strategy! 📞💰

Click here to check the price of your home


Feb. 23, 2025

Hidden Gem Neighborhoods in South Orange County

South Orange County is known for its luxurious coastal cities and master-planned communities, but some of the best places to live remain under the radar. These hidden gem neighborhoods offer great value, charming atmospheres, and excellent amenities without the premium price tag of more well-known areas. If you're searching for an amazing place to call home, consider these underrated communities in South Orange County.

1. Rancho Mission Viejo – The Newer Master-Planned Retreat

✅ Why It’s a Hidden Gem: A newer development offering modern homes, excellent schools, and resort-style amenities at a more affordable price than neighboring areas.
🏡 Home Types: Single-family homes, townhomes, and 55+ communities
💰 Average Home Price: $900K – $1.5M
🌟 Highlights: Clubhouses, pools, hiking trails, and close-knit community events.

Click Here to Search Rancho Mission Viejo For Sale

2. Laguna Audubon (Aliso Viejo) – Quiet Hillside Living

✅ Why It’s a Hidden Gem: Nestled in the hills of Aliso Viejo, this serene community offers stunning views, well-kept parks, and easy access to major freeways.
🏡 Home Types: Single-family homes and condos
💰 Average Home Price: $850K – $1.3M
🌟 Highlights: Award-winning schools, hiking trails, and proximity to Laguna Beach.

Click Here to Search Laguna Audubon For Sale

3. Niguel Summit (Laguna Niguel) – Ocean Views Without the Price Tag

✅ Why It’s a Hidden Gem: This tucked-away neighborhood offers breathtaking ocean and canyon views at a lower cost compared to coastal areas.
🏡 Home Types: Luxury homes, townhomes, and estates
💰 Average Home Price: $1.2M – $2M
🌟 Highlights: Scenic walking trails, large lots, and easy access to Dana Point.

Click Here to Search Niguel Summit For Sale

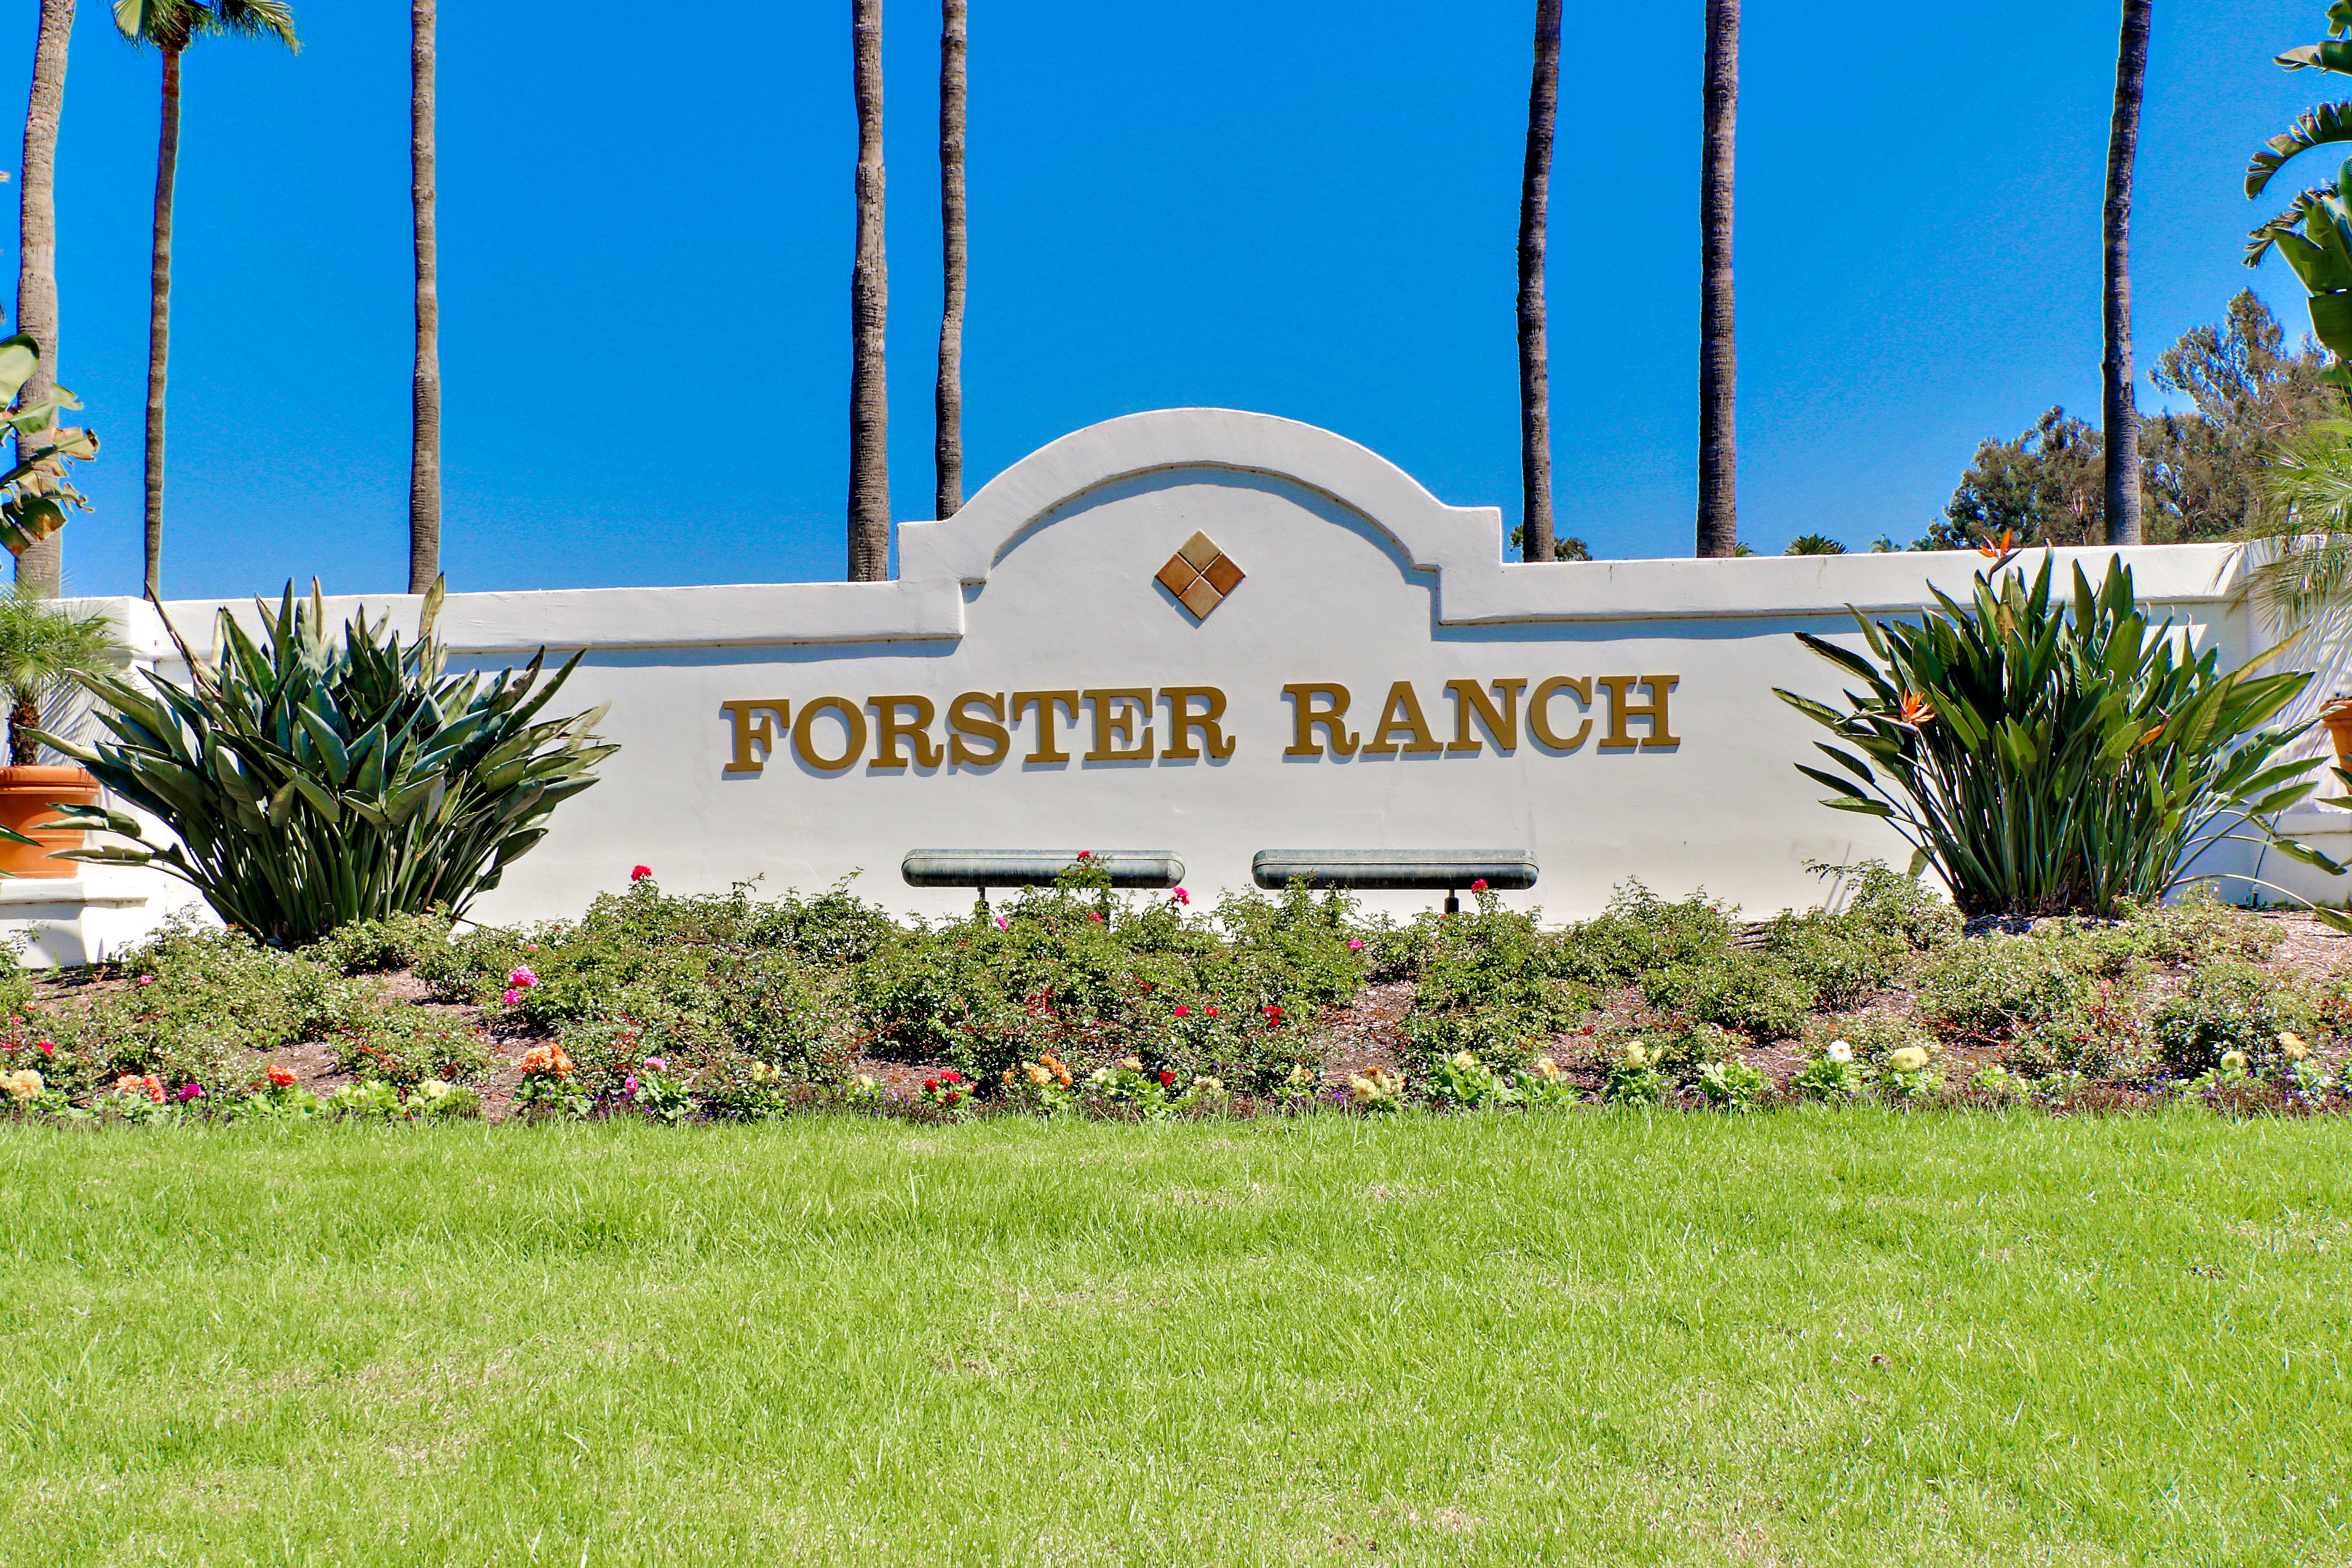
4. Forster Ranch (San Clemente) – A Coastal Escape with Space

✅ Why It’s a Hidden Gem: Unlike many beach cities, Forster Ranch provides larger lot sizes, a suburban feel, and affordability compared to downtown San Clemente.
🏡 Home Types: Single-family homes, estates, and townhomes
💰 Average Home Price: $1M – $2M
🌟 Highlights: Equestrian trails, award-winning schools, and a short drive to the beach.

Click Here to Search Forster Ranch For Sale

5. Ladera Ranch’s Avendale Village – The Best of Both Worlds

✅ Why It’s a Hidden Gem: While Ladera Ranch is well-known, Avendale Village remains an underrated enclave with tree-lined streets, front-porch living, and community charm.
🏡 Home Types: Single-family residences and townhomes
💰 Average Home Price: $900K – $1.5M
🌟 Highlights: Community parks, pools, and top-rated schools.

Click Here to Search Avendale Village


Find Your Hidden Gem in South Orange County

Whether you're looking for a coastal retreat, a family-friendly neighborhood, or a modern master-planned community, South Orange County has hidden gems waiting to be discovered. If you're ready to explore these neighborhoods, contact us today to find your perfect home! 🏡✨

Fill out our New Buyer Survey and we'll find your next home for you.

Feb. 22, 2025

How to Price Your Home Right: Avoid Overpricing & Undervaluing

Pricing your home correctly is one of the most crucial factors in ensuring a successful sale. Set the price too high, and you risk scaring away potential buyers. Set it too low, and you could leave money on the table. Finding that sweet spot can make all the difference in how fast your home sells and how much profit you make.

Click Here to Check the Price of Your Home

Why Pricing Matters 📊

The right price attracts serious buyers, generates competitive offers, and prevents your home from sitting too long on the market. Here’s what happens when pricing goes wrong:

Overpricing 🚨: Leads to fewer showings, extended time on the market, and possible price reductions, which can make buyers suspicious.

Underpricing 🏷️: Can lead to a quicker sale but may mean losing out on potential profits.

Factors That Influence Pricing 💡

When determining the best listing price, consider these key factors:

🔹 Market Conditions – Is it a seller’s market (high demand, low inventory) or a buyer’s market (more inventory, fewer buyers)?

🔹 Comparable Sales (Comps) – Look at recent sales of similar homes in your neighborhood.

🔹 Home Condition & Upgrades – Newly renovated homes tend to sell for more, while outdated features may require a price adjustment.

🔹 Location & Neighborhood – Desirable school districts, proximity to amenities, and community appeal can affect pricing.

🔹 Seasonality – The time of year can impact buyer demand and how quickly homes sell.

Pricing Strategies for a Quick & Profitable Sale 🏡💰

Here are some proven pricing strategies that can help you sell your home effectively:

✅ Competitive Pricing – Price your home slightly below market value to create urgency and attract multiple offers.

✅ Psychological Pricing – Listing at $999,000 instead of $1,000,000 can make a home seem more affordable in searches.

✅ Price Banding – Avoid common price brackets where competition is high and place your home in a less saturated range.

✅ Use a Professional CMA (Comparative Market Analysis) – Work with a real estate agent to determine the best price based on data-driven insights.

How Pricing Affects Days on Market (DOM) ⏳

Homes priced correctly typically sell within 30-60 days. Here’s what happens when pricing is off:

Overpriced Homes 📉: Can sit for 90+ days, leading buyers to think something is wrong, forcing price reductions.

Correctly Priced Homes ✅: Receive offers within the first few weeks.

Underpriced Homes 🚀: Sell quickly but may leave money on the table if not strategically priced.

Adjusting the Price if Needed 🔄

If your home isn’t getting offers within the first 30 days, it may be time to reevaluate your price.

🚩 Signs You Need a Price Adjustment:

Low foot traffic at showings 👣

No serious inquiries or offers 📉

Homes in your area are selling faster than yours ⏳

Final Thoughts: Work with a Local Expert 👨‍💼🏡

A local real estate expert can help you determine the best listing price, analyze market trends, and maximize your sale price. If you’re considering selling your home in South Orange County, reach out today for a free home valuation and expert pricing strategy!

📩 Contact us today to get started!